GST E-Invoicing: Does the ₹5 Crore Limit Apply to Your Business?
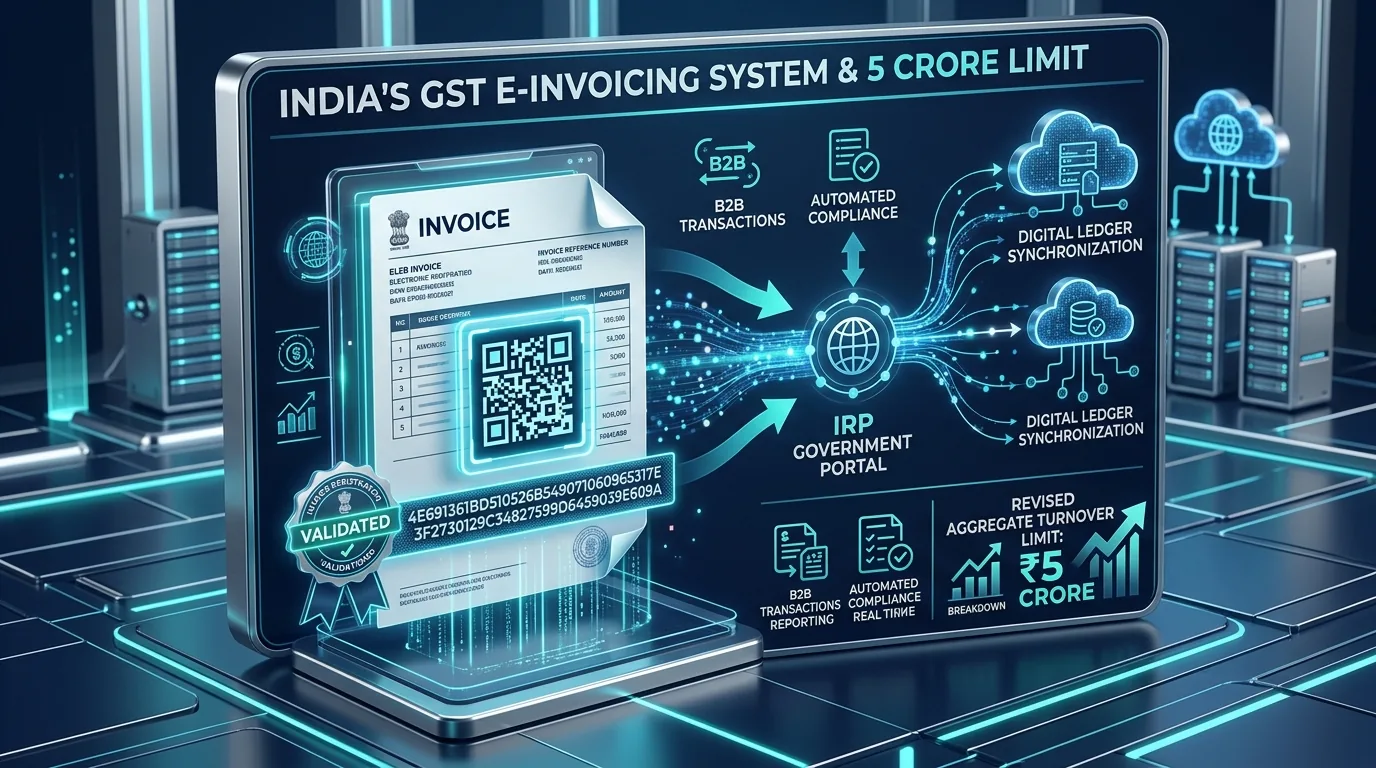
The GST e-invoicing mandate presently covers notified taxpayers meeting the prescribed turnover criteria. The threshold was reduced to ₹5 crore from 1 August 2023 for the relevant notified class of taxpayers. Crucially, applicability depends on historical aggregate turnover from FY 2017-18 onwards, not just current-year sales.
Understanding the ₹5 Crore E-Invoicing Mandate
Under the phase-wise implementation of electronic invoicing under GST, the government reduced the turnover threshold for mandatory e-invoicing to ₹5 Crore with effect from August 1, 2023.
While many enterprise organizations have successfully adapted, micro, small, and medium enterprises (MSMEs) frequently misunderstand how applicability is calculated under the statutory notifications.
Mistake #1: Checking Only Current Financial Year Turnover
The single most dangerous misconception is:
*"My company's sales this year are only ₹3.5 Crore, so e-invoicing does not apply to us."*
The statutory notifications issued by CBIC mandate that:
If your Aggregate Turnover exceeded ₹5 Crore in ANY preceding financial year from FY 2017-18 onwards, e-invoicing becomes permanently applicable to your business.
#### Illustrative Example:
- FY 2019-20 Turnover: ₹5.2 Crore
- FY 2020-21 Turnover: ₹4.1 Crore
- FY 2021-22 Turnover: ₹3.8 Crore
- Current Year Turnover: ₹3.2 Crore
Even though turnover in the last three years has been well below ₹5 Crore, this company must mandatorily issue e-invoices because its turnover exceeded ₹5 Crore in FY 2019-20.
Mistake #2: Calculating Turnover Per GSTIN Branch
If an enterprise operates separate GST registrations across different states (e.g., Kerala, Tamil Nadu, Karnataka) under a single PAN:
- Turnover is not evaluated branch-by-branch;
- Applicability is evaluated on the basis of Aggregate Pan-India Turnover across all registrations under the same PAN; and
- If the cumulative turnover across all branches crosses ₹5 Crore in any relevant financial year, e-invoicing applies to every individual branch.
What Exactly Is an E-Invoice?
A common myth is that e-invoicing requires generating sales bills directly on a government portal.
That is incorrect.
An e-invoice is generated in your normal accounting software or ERP (such as Tally, Zoho Books, SAP, or QuickBooks). The invoice JSON data is then transmitted electronically to an approved government Invoice Registration Portal (IRP).
The IRP verifies the invoice structure and instantly returns:
- A unique 64-character Invoice Reference Number (IRN);
- A digitally signed QR Code; and
- A digital signature from the IRP.
Your ERP automatically embeds the IRN and QR code onto your final printed or PDF tax invoice before dispatching it to the customer.
Which Transactions Require E-Invoicing?
E-invoicing is mandatory for:
- Business-to-Business (B2B) taxable supplies of goods and services;
- Supplies to Special Economic Zones (SEZ Developer / SEZ Unit);
- Export of goods and services (with or without payment of tax); and
- Deemed exports, Credit Notes, and Debit Notes issued for B2B transactions.
E-invoicing is not required for Business-to-Consumer (B2C) retail supplies.
Exempted Categories Under E-Invoicing
Regardless of turnover, the following entities are specifically exempted from the e-invoicing mandate:
- Banking companies, financial institutions, and NBFCs;
- Insurance companies;
- Goods Transport Agencies (GTA) supplying road transportation services;
- Suppliers of passenger transportation services;
- Providers of admission to exhibition of cinematograph films in multiplex screens; and
- Special Economic Zone (SEZ) manufacturing units.
Consequences of Issuing an Invoice Without an IRN
Under Rule 48(5) of the CGST Rules:
*Any invoice issued by a taxpayer to whom e-invoicing applies, without obtaining an IRN from the IRP, shall not be treated as a valid tax invoice.*
Severe practical consequences:
- Buyer ITC Blocked: Your B2B client cannot legally claim Input Tax Credit on an invoice lacking a valid IRN;
- E-Way Bill Invalidation: Goods transported without a valid IRN-linked e-invoice can be detained by GST flying squads; and
- Statutory Penalties: Under Section 122, a penalty of 100% of the tax due or ₹10,000 (whichever is higher) can be levied for issuing invalid invoices.
Frequently Asked Questions
Akash P R
Business Consultant10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances • D BIZ CONSULTANCY
Business Consultant with 10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances.
Connect with Akash on LinkedInOther Strategic Business Guides
GST Registration Documents in Kerala: How to Avoid Application Rejection
8 min readGST & TaxationGSTR-2B Reconciliation with Purchase Register: How to Match Invoices and Protect ITC
9 min readCompany Law & MCAAOC-4 vs MGT-7: Annual MCA Filing Requirements for Indian Companies Explained
8 min readLLP ComplianceLLP Form 8 and Form 11: Annual Compliance Checklist, Timelines and Late Fee Risks
7 min readLatest Regulatory Bulletins
Speak With Our Senior Business Consultants in Trivandrum & Kochi
D BIZ CONSULTANCY PVT. LTD. provides end-to-end company formation, ROC filings, GST accounting, trademark protection, and statutory compliance. Connect with us for personal advisory at our physical offices or 100% paperless digital onboarding.