AOC-4 vs MGT-7: Annual MCA Filing Requirements for Indian Companies Explained
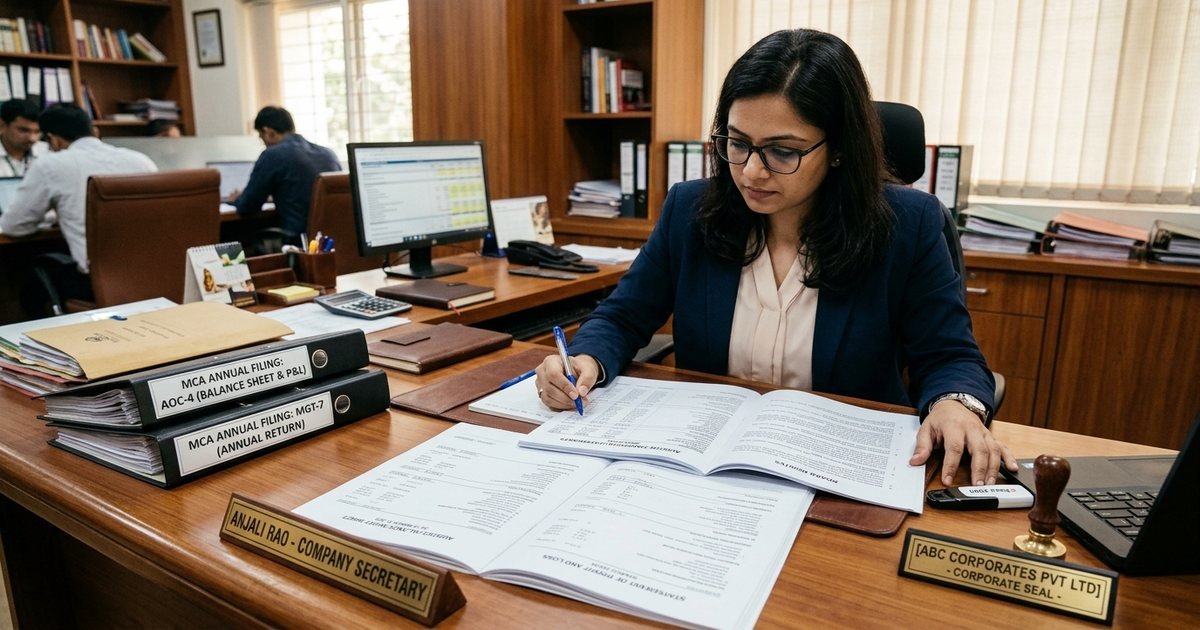
Form AOC-4 and Form MGT-7 (or MGT-7A) are the two mandatory annual e-forms every private limited company must file with the Registrar of Companies (ROC) under the Companies Act, 2013. Form AOC-4 is used to file the company's audited financial statements, balance sheet, profit & loss account, and Board's Report within 30 days of the AGM. Form MGT-7 is the company's Annual Return containing shareholding, director details, and governance structure, filed within 60 days of the AGM. Late filing attracts a continuous penalty of ₹100 per day per form.
Annual MCA ROC Compliance: AOC-4 and MGT-7
Incorporating a Private Limited Company under the Companies Act, 2013 confers limited liability and separate corporate personality. However, maintaining this legal status requires strict adherence to post-incorporation annual filings with the Ministry of Corporate Affairs (MCA) and the Registrar of Companies (ROC, Ernakulam for Kerala companies).
The two foundational annual compliance pillars are Form AOC-4 and Form MGT-7 (or MGT-7A). Understanding their legal distinctions, preparation workflows, and statutory due dates is vital for founders and management boards.
Review our corporate advisory solutions on Company Annual Compliance and Private Limited Company Setup.
1. Comparative Analysis: AOC-4 vs MGT-7
| Parameter | Form AOC-4 | Form MGT-7 / MGT-7A |
|---|---|---|
| Governing Section | Section 137 of Companies Act, 2013 | Section 92 of Companies Act, 2013 |
| Governing Rule | Rule 12 of Companies (Accounts) Rules, 2014 | Rule 11 of Companies (Management & Admin) Rules, 2014 |
| Subject Matter | Financial performance, Balance Sheet, P&L, Audit Report | Corporate governance, shareholding, promoters, meetings |
| Statutory Deadline | Within 30 days of Annual General Meeting (AGM) | Within 60 days of Annual General Meeting (AGM) |
| Typical Due Date | 30 October (for AGM held on 30 September) | 29 November (for AGM held on 30 September) |
| Small Company Form | Form AOC-4 (Standard or CFS) | Form MGT-7A (Abridged return for Small Co & OPC) |
| Certification | Signed by Directors & Certified by CA/CS/CMA | Signed by Director; certified by PCS (if non-small company) |
2. Mandatory Attachments for Form AOC-4
When preparing Form AOC-4 for MCA V3 submission, the following documents must be compiled and formally signed using Class-3 Digital Signature Certificates (DSC):
- Balance Sheet, Statement of Profit & Loss, and Cash Flow Statement: Duly signed by at least two directors (or one for OPC).
- Notes to Accounts: Including significant accounting policies, contingent liabilities, and related party disclosures under Section 188.
- Independent Auditor's Report: Issued by the statutory auditor, complete with Unique Document Identification Number (UDIN).
- Board's Report (Section 134): Including management discussions, director details, transfer to reserves, dividend recommendations, and CSR disclosures.
- Form AOC-2: Disclosure of particulars of contracts/arrangements with related parties.
3. Mandatory Disclosures in Form MGT-7 / MGT-7A
Form MGT-7 captures the ownership, governance, and capital lifecycle of the enterprise during the financial year:
- Principal business activities and national industrial classification (NIC) codes;
- Details of holding, subsidiary, joint venture, and associate companies;
- Shareholding pattern (promoters, institutional, public, foreign direct investment);
- Indebtedness and charges registered under Section 77;
- Number of Board Meetings and Committee Meetings held, with director attendance percentages;
- Remuneration of directors and key managerial personnel (KMP);
- Penalties, compounding, or non-compliance notices during the year.
4. Harsh Legal Consequences of Default
Delaying or skipping MCA annual filings carries severe monetary and administrative repercussions:
- Daily Late Fee: A continuous statutory late fee of ₹100 per day per form accrues without any upper ceiling.
- Substantive Penalties: The company is punishable with a fine of ₹10,000 plus ₹100 per day of continuing failure (up to ₹2,00,000 for company and ₹50,000 for each officer in default).
- Director Disqualification: Under Section 164(2)(a), non-filing for three consecutive years results in director debarment for 5 years and deactivation of Director Identification Numbers (DIN).
- Strike-off Risks: ROC holds the power to initiate suo-motu strike-off under Section 248 if business operations are deemed dormant.
For timely MCA filings, Secretarial Audits, and ROC resolutions, engage the D BIZ Secretarial Team.
Frequently Asked Questions
Akash P R
Business Consultant10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances • D BIZ CONSULTANCY
Business Consultant with 10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances.
Connect with Akash on LinkedInOther Strategic Business Guides
GST Registration Documents in Kerala: How to Avoid Application Rejection
8 min readGST & TaxationGSTR-2B Reconciliation with Purchase Register: How to Match Invoices and Protect ITC
9 min readLLP ComplianceLLP Form 8 and Form 11: Annual Compliance Checklist, Timelines and Late Fee Risks
7 min readIncome Tax & AuditTax Audit Applicability Under Section 44AB: Turnover Limits and Presumptive Taxation Rules
9 min readLatest Regulatory Bulletins
Speak With Our Senior Business Consultants in Trivandrum & Kochi
D BIZ CONSULTANCY PVT. LTD. provides end-to-end company formation, ROC filings, GST accounting, trademark protection, and statutory compliance. Connect with us for personal advisory at our physical offices or 100% paperless digital onboarding.