GSTR-1, GSTR-3B and GSTR-2B Reconciliation Changes Proposed for April 2027
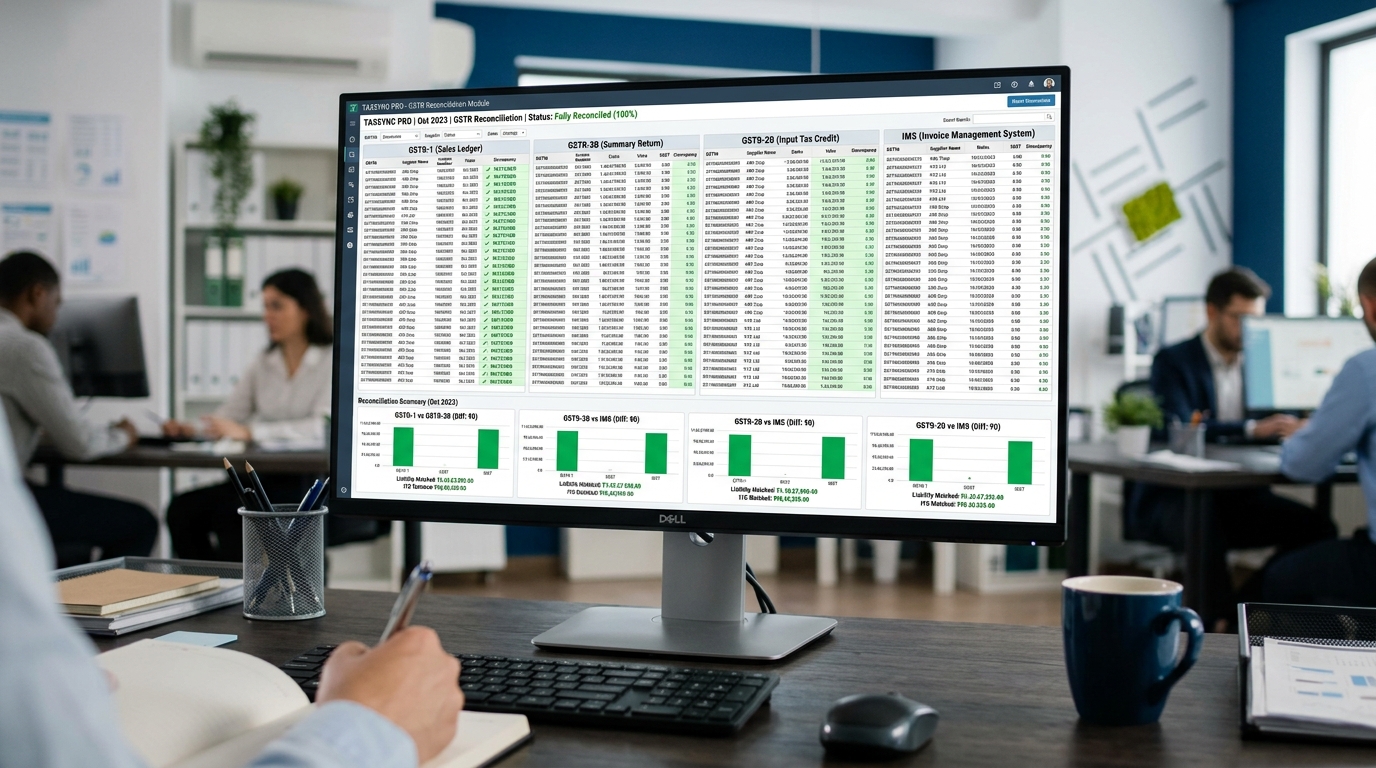
The 57th GST Council approved a comprehensive return overhaul scheduled for rollout in April 2027. It introduces real-time cross-reconciliation between GSTR-1, GSTR-1A, and GSTR-3B, upgraded Invoice Management System (IMS) capabilities to accept or reject supplier invoices, an electronic ledger for tracking credit reversals and reclaims, and structured invoice-level reporting in Form GST DRC-03.
Published Date: 8 October 2026
Editorial Review: Akash P R, Business Consultant (10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances), D BIZ CONSULTANCY PVT. LTD.
News Summary & Quick Answer
Differences between outward sales declarations (GSTR-1), auto-generated credit statements (GSTR-2B), and monthly tax payments (GSTR-3B) generate millions of automated mismatch notices under Rules 88C and 88D every month. Addressing these systematic frictions, the 57th GST Council recommended introducing an integrated reconciliation and return correction framework scheduled for nationwide implementation from the April 2027 return period.
Architectural Upgrades in the 2027 Return System
| Return Component | Current System Functionality | Proposed April 2027 Enhancement |
|---|---|---|
| GSTR-1 vs GSTR-3B Liability | Variances trigger immediate automated DRC-01B intimations | Built-in correction & rectification mechanics prior to payment |
| Invoice Management System (IMS) | Optional document review mechanism | Enhanced controls to accept, reject, or keep disputed invoices pending |
| Credit Reversals (Rule 37/38/42) | Maintained via disparate manual accounting spreadsheets | Official Electronic Credit Reversal & Reclaim Statement ledger |
| Reverse Charge (RCM) Tracking | Self-declared lump sum in Table 3.1(d) | Dedicated statement linking RCM payments to admissible ITC |
| Form GST DRC-03 | Lump-sum voluntary payment filing | Invoice-level tagging to settle specific disputed tax entries |
Operational Implications for Finance Teams
1. Shift from Post-Filing Dispute to Pre-Filing Validation
Currently, businesses often discover reporting mismatches months later when automated notices arrive. The April 2027 framework will flag and reconcile invoice differences inside the portal before final submission.
2. Strict Supplier Accountability via Upgraded IMS
Companies can actively accept or flag vendor invoices inside the portal. Invoices flagged as pending will not inappropriately inflate auto-generated liabilities or distort ITC balances.
3. Transparent Historical Reversals
The electronic reversal register provides a reliable, system-validated ledger for claiming back ITC on supplier invoices paid within the 180-day window under the second proviso to Section 16(2).
Action Plan: Preparing Accounting Systems Ahead of 2027
- Adopt Continuous Monthly Reconciliation: Do not postpone books vs. GSTR-2B reconciliation to annual return season. Utilize automated tools to catch discrepancies monthly.
- Standardize Credit Note Tracking: Ensure sales returns and rate difference credit notes are acknowledged and matched with vendor books.
- Upgrade ERP & Accounting Software: Ensure internal billing systems are configured to export structured invoice-level JSON schemas ready for IMS interaction.
Explore Related Coverage:
Frequently Asked Questions
Practical answers to common business questions regarding this statutory update.
Akash P R
Business Consultant
10 Years+ Experience in Startup Consultancy, Direct Tax, Indirect Tax and Compliances
D BIZ CONSULTANCY PVT. LTD.
Have questions about this compliance update or require assistance with filing before the due date? Connect directly with our advisory desk:
TC No 44, 913, Cotton Hill Rd, Cotton Hill, Vazhuthacaud, Trivandrum 695014.
Plus Code: GX39+M6 Thiruvananthapuram, Keralam
Koprambil Heights, Seaport-Airport Rd, Irumpanam, Thrippunithura, Kochi.
Other Regulatory Bulletins
57th GST Council Meeting 8 October 2026: Key Decisions and Business Impact
8 OctTax & GSTGST Arrest Powers Proposed to End: ₹5 Crore Prosecution Threshold Explained
8 OctTax & GSTGST Refund Reforms 2026: Automated Processing and Impact on Business Cash Flow
8 OctTax & GSTGST ITC Changes 2026: Insurance, Catering, Capital Goods and Blocked Credits
8 OctTax & GSTGST Registration and Cancellation Reforms 2026: New Business Benefits Explained
8 OctAvoid Penalties Under Income Tax & MCA with D BIZ
Whether you require Tax Audit Form 3CA/3CB filing by 21 October, Corporate ITR filing by 21 November, or AGM and DIR-3 KYC compliance, our multi-disciplinary team in Thiruvananthapuram and Ernakulam guarantees timely execution.